Pressure builds on the new home market
September brought little relief for the new home market: although overall sales rose a modest 1.7% month-over-month, they remained 4.6% below where they stood this time last year. The market showed widespread underperformance despite nearly 40% of builders cutting prices in September, up from 30% in August. Zonda’s September builder sentiment survey reinforced the weakness, with 84% of builders reporting slower-than-expected demand, including 60% who said the slowdown was causing concern.
Mortgage rates have only added to the pressure, crossing the 7% threshold in late September and climbing further into October. Alongside broader economic uncertainty, higher borrowing costs are making it harder for builders to maintain sales without putting additional pressure on margins. Even when the numbers work, though, buyers may hesitate to make such a significant financial commitment if they’re uncertain about their jobs or the broader economy.
“The silver lining we’re seeing in the market today is at the high end,” said Ali Wolf, chief economist for Zonda and NewHomeSource. “Prices in the entry-level and move-up/move-down segments declined in September but rose in the high-end market. That doesn’t mean high-end sales are easy. Rather, it reflects that buyers with greater wealth are better positioned to navigate today’s challenging market.”
New home sales fell further behind last year
Zonda’s new home sales metric counts the number of new home contract sales each month and accounts for both cancellations and seasonality. This metric shows there were 690,215 new homes sold in September on a seasonally adjusted annualized rate. This was a gain of 1.7% from last month and a drop of 4.6% from a year ago. On a non-seasonally adjusted basis, 54,334 homes were sold, 4.6% lower than last year and 3.0% above the same month in 2019.
Incentives remain a key feature of the new home market, helping to sustain sales activity amid ongoing affordability pressures. In September, 63% of new home communities offered incentives on to-be-built homes and 82% on quick move-in supply. Note, these are only publicly available incentives so will underrepresent overall usage.
Pending sales were also subdued
Zonda’s New Home Pending Sales Index (PSI) was created to help account for fluctuations in supply by combining both total sales volume with the average sales rate per month per community. The September PSI came in at 132.0, representing a 6.0% decline from the same month last year. The index is currently 24.2% below cycle highs. On a month-over-month basis, seasonally adjusted new home sales increased 3.4%.
- The markets that posted the best numbers relative to last year were Baltimore (+30.3%), New York (+23.2%), and Tampa (+9.7%). Baltimore was up compared to last year and grew 20.4% month-over-month.
- Inversely, the metros that performed the worst year-over-year were Denver (-40.5%), Washington, DC (-29.0%), and Las Vegas (-17.0%).
- On a monthly basis, Baltimore, Riverside/San Bernardino, and Los Angeles/OC were the best performing markets.
Underperforming markets were widespread
In order to add further context to sales, Zonda created the Zonda Market Ranking (ZMR). The ZMR accounts for both sales pace and volume, is seasonally adjusted, and is taken as a percentage relative to a baseline market average. Based on the percentage above or below baseline, markets are bucketed into performance groups ranging from significantly underperforming to significantly overperforming relative to historical activity.
The map below shows a snapshot of top production markets by region. Zonda also offers the ZMR for entry-level, move-up/move-down, and high-end markets. Subscribers of the National Outlook report can access all top markets and the tiered breakdown in Zonda’s portal. Non-subscribers can access the tiered maps for the select 10 markets by clicking below.
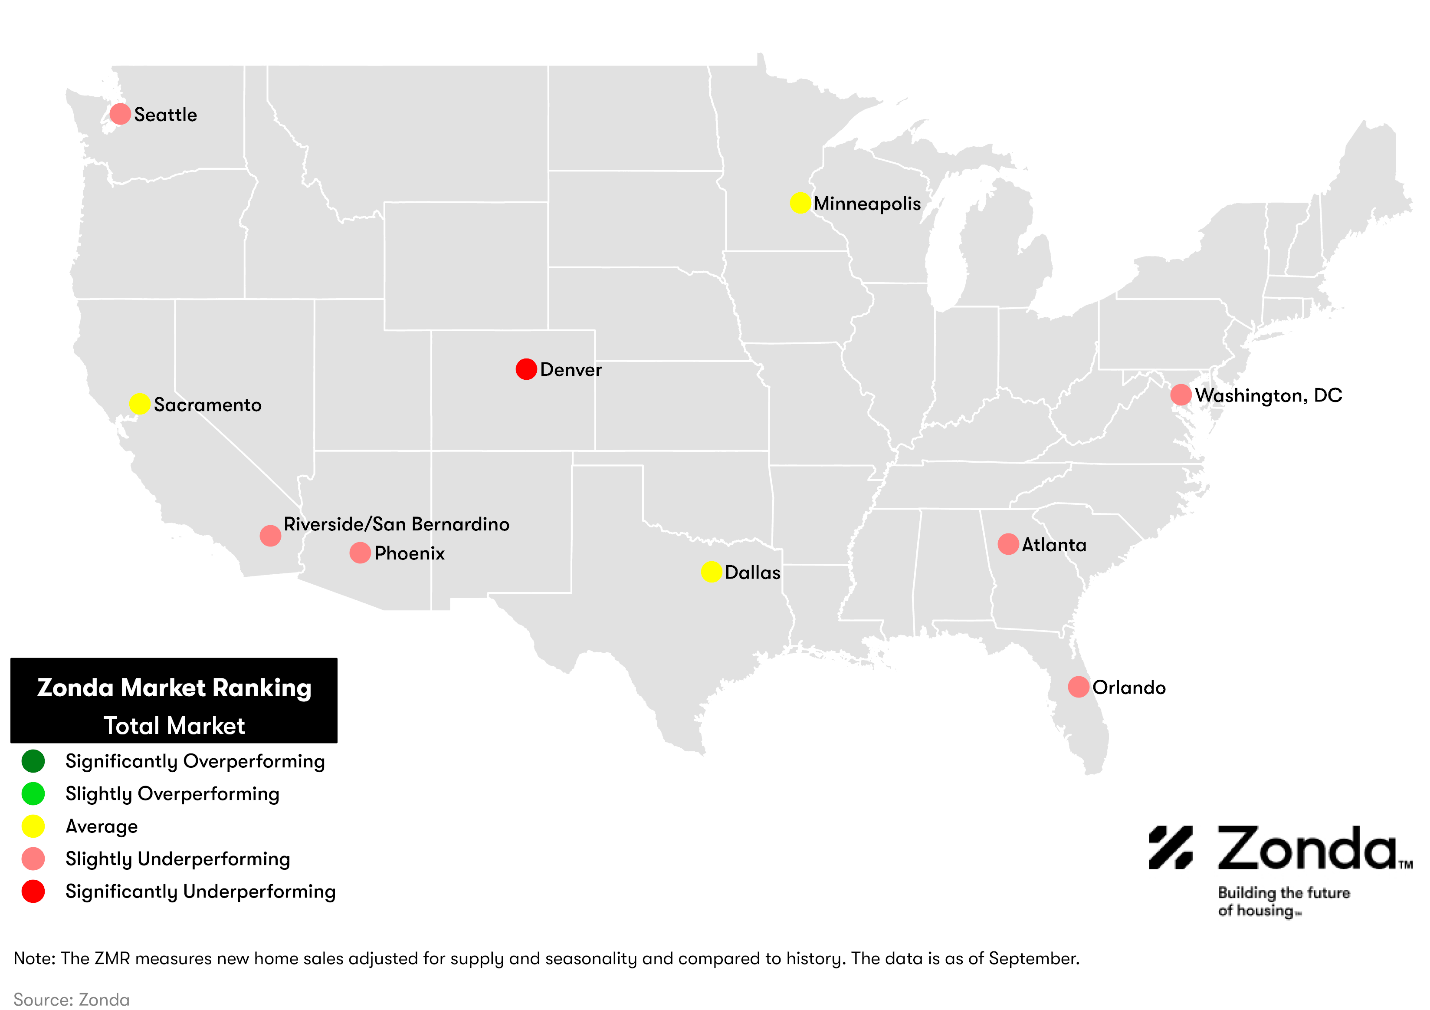
- The National ZMR index came in at 95.8 in September, which continued to indicate an average market.
- Zonda’s snapshot markets were split between 0% overperforming, 30% average, and 70% underperforming. Among Zonda’s top 55 major markets, 14% were overperforming, 33% were average, and 53% were underperforming.
- Importantly, the ZMR does not account for what it takes to sell a home. For example, securing a sale might still feel difficult in a significantly overperforming market, but if the incentives offered result in a sale, we count the sale.
More builders turned to price cuts
National home prices increased 2.0% year-over-year for high-end homes to $946,207. Prices fell 2.6% for entry-level to $316,246 and 0.8% for move-up to $513,294. The increase among higher-priced homes reflects a concentration of new communities opening at premium price points, along with larger homesites, bigger floor plans, and more desirable locations. Meanwhile, modest price declines in the entry-level and move-up segments suggest builders continue to prioritize affordability through incentives, product right-sizing, and more competitive pricing in response to softer buyer demand.
Supplementing our data with a survey Zonda conducts monthly, 38% of builders lowered prices in September month-over-month, 52% held prices flat, and 10% raised prices. In August, for comparison, 30% of builders lowered prices, 63% held prices flat, and 7% increased prices.
Community count up 6.5% from last year
There are currently 18,143 actively selling communities tracked by Zonda, up 6.5% year-over-year. On a month-over-month basis, the national figure grew 0.8%. Total community count is 6.0% below the same month in 2019. Zonda defines a community as anywhere five or more units are for sale.
- San Jose (+46.9%), Miami (+39.6%), and Greenville (+18.2%) grew community count the most year-over-year.
- Relative to last year, the biggest community count declines were in Cape Coral (-15.4%), Portland (-13.7%), and Reno (-12.0%).
National quick move-ins (QMIs) totaled 38,214, up 3.5% compared to last year but 0.8% lower month-over-month. Over the past 18 months, builders have taken a more measured approach to spec home construction to avoid adding excess inventory amid a more challenging sales environment. Total QMIs are 66.2% above 2019 levels. QMIs are homes that can likely be occupied within 90 days.
- On a metro basis, 52% of Zonda’s select markets increased QMI count year-over-year.
- The markets that grew the most year-over-year were Philadelphia (+46.8%), San Francisco (+40.9%), and Cincinnati (+35.0%).
- Cincinnati, Las Vegas, and Phoenix have seen the most growth in QMIs compared to the same time in 2019, up 315.7%, 282.4%, and 189.0%, respectively.
QMIs per community is a good way to track how new home supply looks in the context of actively selling projects. There were 2.2 QMIs per community nationally in September, down 2.0% compared to the same month last year.
Please note, the QMI per community data aligns with this report covering September trends. Our quick move-in data is weekly, and we release the latest available at the time of publishing this report. As such, recreating the visual below with the data above will yield slightly different results.
Are you interested in seeing past National Housing Market Update and Pending Sales Index reports? Access our report library to learn more.
Methodology
The Zonda New Home Pending Sales Index (PSI) is built on proprietary, industry-leading data that covers 85% of the production new home market across the United States. Reported number of new home pending contracts are gathered and analyzed each month. Released mid-month, the New Home PSI is a leading indicator of housing demand compared to closings because it is based on the number of signed contracts at a new home community. Zonda monitors 18,000 active communities in the country and the homes tracked can be in any stage of construction.
The new home market represents roughly 10% of all transactions, allowing little movements in supply to cause outsized swings in market activity. As a result, the New Home PSI blends the cumulative sales of activity recently sold-out projects with the average sales rate per community, which adjusts for fluctuations in supply. Furthermore, the New Home PSI is seasonally adjusted based on each market’s specific seasonality and removes outliers to reduce volatility. The index was re-benchmarked in June 2026, so PSI readings may differ from those reported in prior releases.
About Zonda
Zonda provides data-driven housing market solutions to the homebuilding industry. From builders to building product manufacturers, mortgage clients, and multifamily executives, we work hand-in-hand with our customers to streamline access to housing data to empower smarter decisions. As a leading brand in residential construction, our mission is to advance the home building industry, because we believe better homes mean better lives and stronger communities. Together, we are building the future of housing.